Showing posts with label health care. Show all posts

Friday, November 23, 2018

Compound interest provides $1 million


Can compound interest provide a $1 million retirement?
Are you saving and investing at least $250 a month in your retirement at work (401k, 403b) or IRA on your own? Are you putting most of the money in low-cost stock mutual funds? The other variable is time. Compound interest works when you have time on your side. It takes about 33 years ($250 a month, $3,000 a year) with total contributions of only $99,000 to reach $1,000,000. Even if you begin after age 30, you can still have much more than almost all your neighbors. According to Warren Buffett, “My wealth has come from a combination of living in America, some lucky genes, and compound interest.” Mr Buffett recommends we use low-cost funds like those at Vanguard. He confirms that compounding works over time if we do not try to time the market or trade the ‘hot’ securities. Look at any 33 year period of stock earnings. You earn 10-12%: http://www.moneychimp.com/features/market_cagr.htm. Go with Buffett’s ‘Secret’.


What about ETF up 35% this year?
What are the gurus and TV marketing people so happy about? Your plain low-cost broad market index that Buffett recommends is flat for 2018. So what can financial people talk about? How about gold (JDST): Return year-to-date: 48.79%; One-month return: 28.66%. But after you look further, the three-year return is -77.62%. Natural gas? (UGAZ): Return year-to-date: 51.62%; One-month return: 22.37%. But three-year return: -51.43%. How about muni bonds (EVLMC)?: Return year-to-date: 100.76%; One-month return: 0.11%. No track record for a three-year return: N/A. So what about Treasuries (DLBS)?: Return year-to-date: 37.96%; One-month return: -0.74%. Not much better than your bank savings account in three-year return: 0.24%. 500 Index (VFIAX)?: Return YTD: 3.83%; 5 year: 11.3%; 10 year: 13.22%. Salespeople always have ‘shiny objects’.

Do you need a REAL middle-income tax break?
The REAL tax break from the GOP and Trump is the removal of the income cap on conversions from traditional IRAs to Roth IRAs. The 1.6% income increase for the average household earning $50,000 to $75,000 has been eaten up by tariffs and health care costs. Compare the $thousands you save in taxes during retirement when most of your income is tax-FREE and you no longer have to take taxable RMDs from your IRAs. For many, the elimination of tax on IRA distributions means their income can continue to grow after 70 ½ AND they will pay less tax or nothing on their SS benefits.

Health ins plan scams prey on the most vulnerable
“You can now get a great insurance plan at the price you can afford. We make it hassle free to sign up with the policies from Signa Blue Cross Etna United and many more. Press one now to get a hassle free assessment or press two to be placed on our do not call list. Thank you and it’s always be happy blessed.” Criminals promise inexpensive health care plans and take personal information that’s used to commit identity theft. In another version, victims are sold useless healthcare discount plans that scammers frame as cheaper than the consumers’ current health insurance. A Florida-based company named Simple Health Plans allegedly collected $100 million from tens of thousands of victims, Federal Trade Commission lawsuit.  Consumers paid up to $500 a month for a relatively worthless product, the agency said.

Do you own the absolute WORST funds?
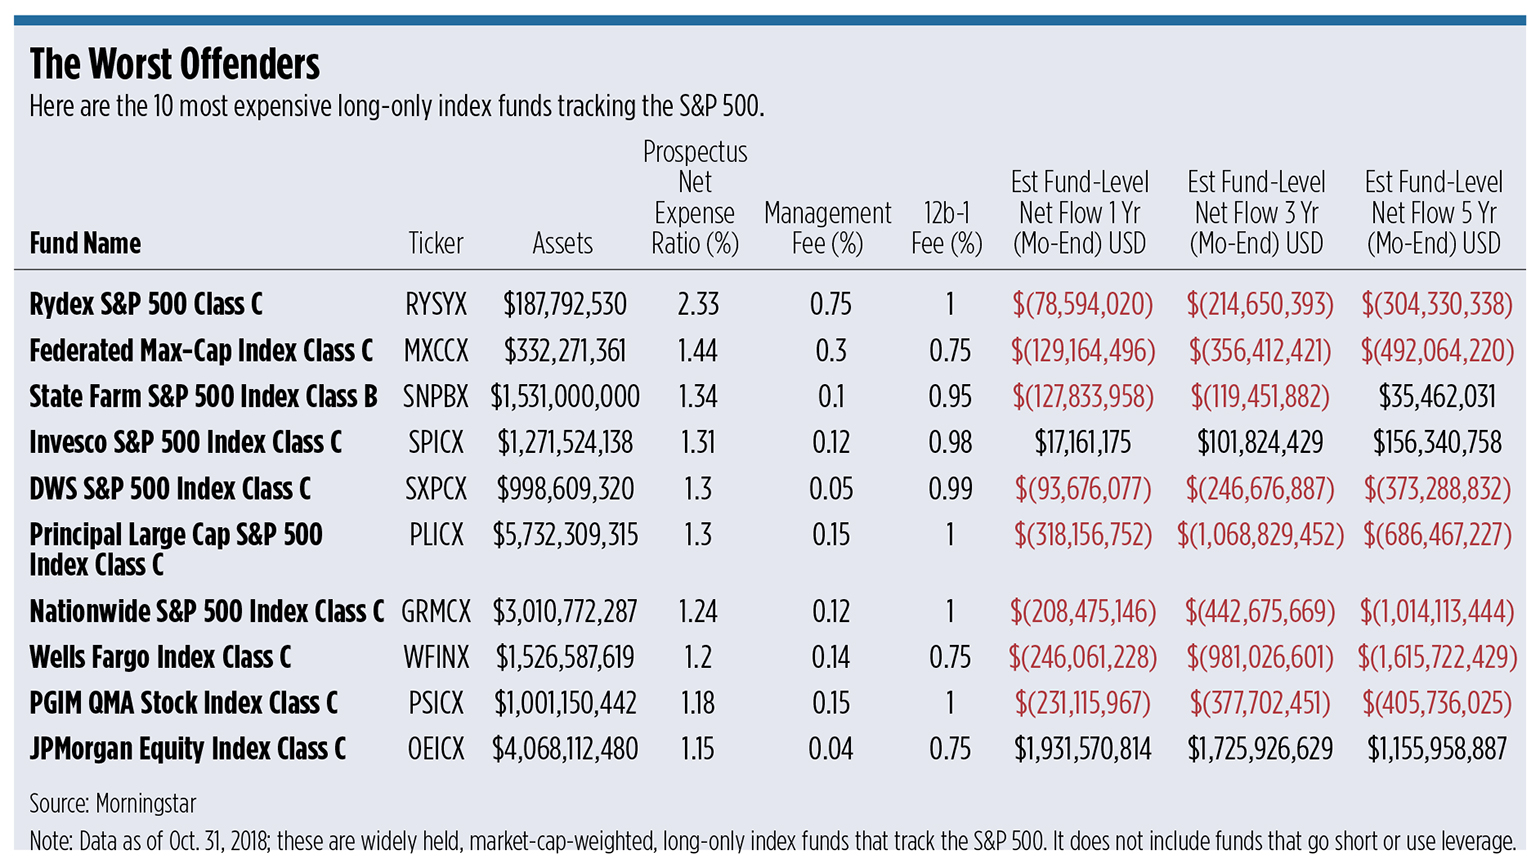
Why do people pay much more for exactly the same commodities as others? Convenience? Inertia? B.S.? Misleading benefits? Some advisors are charging 2.33% for the same product as others charge 0.00%. Is that a ‘loss leader’? Sellers need to make something in order to compensate for time spent on other services they say. State Farm charges 1.34% for their plain 500 index fund. Do their customers believe they are buying an insurance product? Many insurers seem to be enjoying this extra profit. Perhaps customers are finally getting the message—net flows are negative for 3 and 5 years. Customers who feel more informed have chosen to separate financial providers/vendors. Vanguard, not brokers, offered the index in 1976 for less. It is now the largest mutual fund firm for a reason—costs matter. 11% vs 3.79% return on your money is huge.  

Another way the ‘Tax Credit’ class avoids paying their fair share
The IRS just issued proposed regulations stating that there will be no clawback of the use of any unified credit (gift tax exemption) before 2026 when the lifetime exemption will revert from $10 million to $5 million. Wealthy taxpayers may safely use the current $5+ million excess and, if death occurs after 2025, still have $5 million for estate tax purposes, thanks to the millionaire Congress. Similarly, a taxpayer could make a taxable gift now of $11.18 million without concern that there would be a phantom estate tax on their death after 2025. Passing on $11.18 million tax-free allows the kids to get the ‘head start they really need’? to create their own tax-advantaged business.


****************

Make America, “The Don”, Great Again

Two Americas: A Banana Republic? Do we really want an infant king? Daddy Putin!

***********************

How Govt wastes our money: Congress spends $1.3 Trillion we don’t have! 
Trump’s stunt over: 5,800 troops not home for Thanksgiving. Cost us $220 million.

SCAMS/SPINS:
RoboCallers index: Top 100 callers by volume https://robocallindex.com/top-robocallers
Hackers control your pacemaker? Any electronic implant can be controlled by others.

First Choice Healthcare Solutions caught ‘pump and dump’ stock scam: $12.5 mil lost.
Elite Stock Research caught ‘pump and dump’ stock scam: $10. mil lost.
Giga Entertainment caught paying others to pump up sales software on Apple Store.

Check food: banned flavors--methyl eugenol, benzophenone, ethyl acrylate and pyridine.
Ford’s robot cars: “When we take the road, we know what doing and where the profit is.”
Trump attacks another distinguished patriot: draft dodger says he could have done better.

Cheryl Ann Stallings caught controlling client bank accounts for profit
Scott Newsholme, FL caught stealing $3.1 million by various fraud: jail 8.5 years

H. Beck MD caught allowing sale of unsuitable L-share variable annuities/riders. No jail.

The Don SAYS HE'S MOST THANKFUL FOR HIMSELF ON THANKSGIVING


----------------------------------
The Mob Boss can never go to jail: Trump has Kava as Supreme so no indictment.
‘No man is above the law’ … well up till now. Dictators nullify courts first, then votes.
Supremes protect Don’s ‘Orders’? – GOP: Sure, pres can change Constitution anytime.
----------------------------------

Jobs:


Who owns your account now?
Avoid mistakes like these in passing on your accounts and assets.

Foxconn coned WI into $4.1 BILLION subsidy: now orders down but taxpayers billed.

Miracle:
Where is the miracle that stops mass killings? More crazy people or mass destruction weapons?

20 million more of us have health insurance than in 2010! 28.5 million still not covered. We can do better: All the children in New England are insured. 


“Mick and I live off of this fire between us” New rule: work past age 75 for a grand life.

IAN
41 Watchung Plaza, B242
Montclair, NJ   07042
973.746.2014
Alerts 

Friday, October 26, 2018

Tax-FREE retirement is winning the 'lottery'


Tax-FREE Roth 401k or Roth IRA?
If you are lucky enough to have the Roth 401k offered by your employer, you must understand the pros and cons of both Roth accounts. In both, you never pay tax on your retirement accumulations. So if you can aggressively fund your Roth 401k, you could easily reach $1 million tax free because your $100,000 total contributions over time can COMPOUND at 10% by age 67. If you can invest just $9 a day, $250 a month, you can still have $1 million tax free at age 67, you just have to start earlier. If you can’t do a Roth IRA because of limits, try a ‘back-door’ Roth. COMPOUNDING at the long-term stock market rate of 10% means your money doubles every 8-10 years. Look at the https://www.bankrate.com/calculators/retirement/roi-calculator.aspx. Most of your tax-free balance will be accumulated capital, not contributions: FREE MONEY.


Winning the $1 million ‘lottery’
$1 million tax free. You can spend it all—no taxes. Usually you must pay HALF your winnings to fed and state gov. $1 million can provide over $100,000 per year for life. Everyone who plays this ‘lottery’ will win. This $1 million lottery is not awarded every week. You must wait. Each week you buy $9 worth of ‘chances.’ You don’t win every week or month but you WILL win eventually. This lottery is a sure thing eventually because you actually are buying a piece of the profits of many successful companies. Some companies make a profit every year and some make a huge profit some years. Over time the ‘chances’ you buy get more valuable. Think about all those tickets of your past losses in the drawer. They are worthless because you did not win and every week you will lose—almost guaranteed. Thank god, you have a better chance of being hit by ‘lightning’ than winning any week. This lottery is not a lottery but a sure way to own $ million worth of all the companies you buy things from—groceries, electronics, toilet paper, electricity, cars, everything. You own Apple, Google, Microsoft, J&J, Facebook, Exxon, Morgan Chase,  Disney, and more. The value of your ‘chances’ go up and the profits the companies pay buy more ‘chances’. Buy from the largest ‘chance’ seller.

Are songs royalty streams right for you?
For those who have a crystal ball, buying the right to receive music royalties might be the alternative investment you have been looking for. Winning bidders typically get royalty payments on a quarterly basis, with a rate of return Royalty Exchange says is often in the double digits. The longevity of the royalty rights varies. Some royalty rights are limited to 10 years, while some offers include copyright ownership, which means the payments can last for decades. Some investors think royalties can never end. Royalty Exchange, the middleperson, launches three to five new auctions every week. Songwriters have a tax incentive for selling. Under the law, the money songwriters make from selling all or parts of their catalogs is treated as capital gains, taxed at 0, 15, or 20%. Royalty revenues, meanwhile, are treated as ordinary income, taxed as high as 39.6%. "There are people whose only real assets are their royalties," he said. "Their financial security is based around how they leverage those things."

Does your broker/advisor live in these states?
Connecticut, Nevada, New Jersey, New York, and other states have passed laws or proposed regulations that mirror some of the federal rule's requirements to treat you with respect. Even though Trump cancelled the Fiduciary Rule—you receive advice/product that is BEST for you not for the institution—these states have or will protect you from outrageous commissions and fees, inappropriate products, and misleading information. Obama said without this law, you and I could give up thousands of dollars when we moved our retirement money (401k, 403b, IRA, pensions). My industry (financial:  http://dankeppel.blogspot.com/) can’t make $millions and $millions by giving you advise without putting our own high-cost products in front of you. In fact, most advisors and their firms don’t even carry the best products for you because they must make money to survive. Everything has changed in the last decade: discount brokerage, discount mutual funds, discount insurance, etc. My friends and I have left the old industry model.

Vital steps to buy a house
Don’t even look for a house before you understand the process. No use frustrating your family if it can’t happen now. Offerings and loan rates change daily. First, check your credit scores at www.myfico.com and errors at www.annualcreditreport.com. Check rates on trial amounts at your bank and then shop around at www.bankrate.com and https://www.quickenloans.com. I used them—very fast and efficient. Big banks have 10 plus people handling your loan and it takes 3 times longer. Second, find out ‘how much can you borrow?’ The final answer depends on your income and the lender, but usually it is monthly costs (mortgage, insurance, and property taxes) can’t exceed 28% of your gross monthly income. Fannie Mae increased its maximum DTI ratio to 50 percent, up from 45 percent, in July 2017. Third, the standard down payment is 20% but you may find exceptions: Federal Housing Administration or the Veteran’s Administration. Fourth, your lender may want you to pay down debt or temporarily reduce spending. If your family helps with the down payment, let it ‘age’ in your account for a few months. Now you know what houses you can afford and can ‘lock in’ a rate/terms. I used www.realtor.com and found a 2 family to help me pay for the mortgage. Timing is everything. Get your loan approved BEFORE you shop so you can pounce.

Is tax lien investing right for you?
Risk you must understand for this kind of game of chance. When a property owner fails to pay property taxes, the municipality in which the property is located can sell its tax lien — the right to foreclose on a property when the owner has failed to pay taxes. So you can force payment plus costs plus profit by threatening to take your neighbor’s house away and sell it. Most tax liens purchased at auction are sold at rates between 3% and 7%. If the owner does not pay you, you get to foreclose which can cost over $10,000. “It’s complicated. You have to understand the details,” according to an observer. Each state is different, so buying and collecting on a lien is how amateurs fail. Compare alternative assets like owning diversified real estate funds: REITs.

Mandate to have health insurance still exists
If you have been without insurance this year because you heard Trump cancelled the mandate, surprise—the mandate penalty is subtracted from your refund unless you qualify for various exceptions. So if you are not owed a refund for 2018, there will never be any consequences for not paying the penalty tax. Trump won’t collect it now. Trump has dismissed comprehensive coverage in his special ‘short-term’ policies. He has made buying coverage without protections easier so that he can claim his plans are “cheaper and better.” Trump does not understand—he has always had it. It is not magic—his plans do NOT cover pre-existing conditions and have payout limits. You may be denied or cancelled. You may have premium increases. Most Americans like ACA now that they have it. If you are lucky, you live in a state that maintains the guarantees of ACA. Before ACA you could buy cheap policies—they were junk and didn’t cover you when you needed it. You can’t buy insurance after you get sick or have an accident. Like car and home insurance, it is a way to share the risk of a huge loss. You pay premiums all your life for a catastrophe you hope won’t happen. The alternative is bankruptcy or destitution.
You need full coverage: Trump has it, why not us?: https://www.amazon.com/Health-Insurance-ONLY-right-policy/dp/1480125083

Consumer Reports: Most reliable vehicles
Your vehicle ratings by brand are not unusual but look closer at all brands for the type—SUVs popular still (even Porsche has one??). Some specific models were dropped from the CR list altogether. Biggest ranking drop: Honda, Chrysler, Volvo, and Tesla. Volvo is now Greely (Chinese), Chrysler is now Fiat and Tesla is still working out the kinks. Vehicles are now mobile entertainment units not transportation. If you need quality reliable transportation not TV screen gadgets, go for a 3 year old thoroughbred like 2016 Lexus or Toyota from $12,500 to $30,000.


****************

Make America, “The Don”, Great Again

Two Americas: A Banana Republic? Do we really want an infant king? Daddy Putin!

***********************

Trump breaks 1987 Reagan arms treaty to spend more on weapons of mass destruction.
GOP promises 2nd tax break as teaser for midterm election of more spendthrift GOP.

TX GOP closes voting sites-long lines and DEMs must take off work. Voting rights?


SCAMS/SPINS:
Chris R. Kubiakk, WI  stole $270,000 from clients’ accounts for personal use.
John G Schmidt OH caught stealing $1.6 million retirement funds from boomers.
Cash Express caught threatening loan collection it can’t make against consumers.

Christopher Faulkner, Breitling, stole $23.8 million promising oil/gas profits.

23andMe’s health reports are dangerously incomplete, geneticist says.
Cancer care marketing misleading—big biz budgets add spin for profits.
Why drug prices keep going up—It costs $200 million to stop Congress from acting.

Trump to close all borders, ports, tourism, trade—any non-white immigrants.

Trump to pardon Charlottesville Nazis?? Neo-Nazi caught trying to flee from law

GA to suppress votes of 1 million ‘non-matching’ voters: aims to erase non-whites.


Saudis kill 100s every day in Yemen—Khashoggi is just a ‘fist fight’—hospital record?


----------------------------------
The Mob Boss can never go to jail: Trump has Kava as Supreme so no indictment.
‘No man is above the law’ … well up till now. Dictators nullify courts first, then votes.
Supremes protect Don’s mob -- Ross’s legal deposition canceled.
----------------------------------

Jobs:

Who owns your account now?
Trump defines gender from now on: you lose free choice—no 2nd Amendment for that.
DIY repair outlawed by GM, Deere, others: we buy it but they own circuits/algorithms.

You can’t uninstall—they own algorithms: track you after ‘uninstall’ Can’t cancel Uber.

Save $ HALF: Compare drug prices in your area: https://www.goodrx.com


Miracle:

Do we really want to keep immigrants out of US? We need new ‘blood’ to survive!

IAN
41 Watchung Plaza, B242
Montclair, NJ   07042
973.746.2014
Alerts

Friday, June 15, 2018

New ways wealthy avoid taxes and we pay theirs


New ways the wealthy avoid taxes and we have to pay their share
The corporate rate was lowered to 21% (effective rate is 12%), so “today we can think about using corporations even though it means two layers of taxes, while historically we might have said that it doesn’t make any sense to have two layers of taxes,” one specialist says. This means the rich avoid 37%, 35% and 32% tax rates with income of $157,500 or more just by taking income as a business. They deduct their expenses as business deductions and pay under HALF the official rate. Even if they have the corporate and individual tax, they design income to the lowest possible level and end up paying less than we do. The wealthy have figured out how to avoid taxes. For instance, Warren Buffett, with $90 billions, pays only 17% total tax: http://www.youtube.com/watch?v=Cu5B-2LoC4s; Mitt Romney only 14%; John Kerry only 13% and Apple just 9.8%. Buffett found that his staff pays 32.9%—DOUBLE their rate!
They can use ‘carried interest’ as a Trader Business of their family office to deduct investment expenses, which were ended by the tax law. And remember, they can deduct their contributions to a deferred comp plan and let the company pay for their rides and entertainment and part of their dwelling. They can use their tax-deductible foundation to pursue hobbies or pay off debts. They can also bunch up their deductions to take full advantage of the new law. Inequality in net worth rises by 2020 election.

Will you have enough?
According to 2016 govt data, “older households” (over 65) spend an average of $45,756 a year, or roughly $3,800 a month. That’s about $1,000 less than the monthly average spent by the average U.S. household. Of course your spending in retirement will vary a lot so it is helpful to compare ‘average’ to your estimates. For instance, housing expenses average $1322 a month. But if you live in a high property tax area, your tax or rent will be more. Rents are above $2,000 in N. NJ. Compare the average in transport, food, personal, insurance, charity, vacations, hobbies, etc. Now, try estimating your SS benefits, pensions, IRAs, 401ks, other income. Average SS benefit we know is $1,342 a month. If you both have similar salary and work records, you can double that--$2,684. That leaves about $1,116 from all your other sources. Don’t use the popular 3% or 4% withdrawal rate—that worked when you could earn 6% at the bank. Markets change every year. You can estimate what you need and then you will know whether you should keep working.
By age 70, you must take your RMD from any tax-deferred plans. You can also increase your SS benefit each year by working past age 66 or 70 because SS recalculates your benefit each year with the HIGHEST 35 years of earnings, including those you earn after you begin receiving benefits. Perhaps you will have a surplus of income over expenses. Check 17 ways to use your RMD: https://www.amazon.com/What-your-RMD-much-spend/dp/1718946716

Why our children don’t know how to invest for the future
Only 5 states require schools to teach financial literacy. They don’t know compounding builds wealth or how to make wealth earnings tax-FREE. This leaves our future adults with no way to secure their future unless they inherit money. Employers are dumping pension plans en masse. In 1983 there were 175,143 plans, but in 2008 there were only 46,926 plans. So most employees have no idea how to replace the plans they have lost or never had. 401k was supposed to be the supplemental plan not the center piece of retirement. Now you know why most people are not ready for retirement and when SS is cut in 2034, this country will have the poor living on the street in the thousands. Warren Buffett is not a salesman for the financial industry so his simple strategy is the best way for our high schoolers to learn compounding and investing. His strategy requires time not big bucks—10% of salary is all the young people need to grow their money to a Wealth Reserve for life. In fact, if they or family contributed $2,000 for 8 years by age 27, they might have over $1 million by retirement just from the Miracle of Compounding.


GOP will end health care for Americans with pre-existing condition
GOP faced town hall outrage as it tried to end ObamaCare. Many people learned to love some benefits of ObamaCare. That included the expansion of Medicaid, allowing young people to stay on their parents’ insurance up to age 26, and forbidding insurance companies from denying anyone coverage or charging them more because of pre-existing conditions, which just about all of us either already have or will one day have.
The popularity of those provisions made repeal politically dangerous, so Republicans decided to leave the popular parts in place and try to repeal only the unpopular parts. Even that, however, proved impossible to do, and in the end they settled for a small morsel: Trump’s tax cut law repealed of the individual mandate by reducing the fine for not carrying insurance to zero.
Now TX leads a new lawsuit from a group of conservative states seeking to strike down the entire ACA. Trump has taken a position in that lawsuit that is just dumb. Trump will not defend the law that requires insurers to cover all his supporters with pre-existing conditions. They will lose coverage because of outrageous premiums on their conditions.
Trump and the GOP will have a hard time in 2018 since most Americans want coverage.

Did you forget to sign up for Medicare on time?
Did you mistakenly stay on your old private insurance plan (ObamaCare) past age 65? You should have switched to Medicare. Now you are stuck with costly lifetime late-enrollment penalties on your Medicare premiums. Until now! You can fix this problem is Sept. 30. If you have health insurance at work, there is no need to worry. You sign up when you retire. This late penalty forgiveness ends soon. Avoid the annual 10% penalty as higher premiums for Part B—doctors. Visit your local SS office to see if you qualify. Read instructions: bit.ly/2Jyzx8s. Bring all your health care paperwork, including evidence that you have been enrolled in a marketplace plan. 
Get all the coverage you already paid for: https://www.medicare.gov/pubs/pdf/10050-Medicare-and-You.pdf


Have you felt the wage increase?
Yes, real (after inflation) wages are going up after years of decline. The larger fact is that real hourly wages have been generally rising since hitting a low point in 1994-95. As of April, they were 19 percent higher than that low point. However, they are 1.5% below the highest point reached in 1972. Average workers’ wages have remained below the high of $9.40 adjusted for inflation. To make it up, we work more low pay jobs. 60% of American children are on Medicare or CHIP because their parents can’t afford health care or don’t receive it at work. Paychecks are rising even faster than hourly wage rates, because part-time workers are finding more work and full-time workers are getting more overtime pay. Inflation-adjusted weekly earnings for production and nonsupervisory employees have risen 1.4 percent under Trump, after rising 3.7 percent under Obama.


SCAMS: Beware the ‘guaranteed interest payments’ scheme
Steven Pagartanis, NY stole $8 million promising guaranteed monthly interest payments to his customers. He said they were invested in Genesis Land Development of Canada. There is such a firm but when I emailed them, they say Pagartanis’ investments are unknown to them. Since 2013 his firm Lombard Securities never checked his promises and no customer ever confronted him. Apparently, Pagartanis kept up the “above market” interest payments until this May. As in many Ponzi schemes, the payments and statements eventually run out ala Madoff. Usually the original investments are spent or hidden by the perp. Lombard is required to supervise its brokers but Lombard apparently has failed with other brokers and their non-traditional securities. Lesson: don’t assume your broker if offering you a legal deal if 1) the deal is great—above the market returns; 2) the firm or broker has a record on BrokerCheck; or 3) you don’t verify your money went to place your broker claims. In this case, you might have suspected something from broker record of not disclosing annuity terms to his client in 2013 and leaving 10 firms and joining 10 firms since 1996. Unfortunately, the industry lets bad eggs move to new firms and bad firms hire them. It is all about making money--caveat emptor and white collar crime is NOT a priority for Sessions and Trump.


Is a safe-deposit box right for you?
Are you really paying $150 a month to the bank—$1,800 a year for a safe place to keep your goods? Over time that is costing you $1.3 million if invested in simple index account like Warren Buffett recommends. That might come in handy if you face unexpected medical or long-term care expenses 30-40 years from now. Consider that you already have insurance to cover jewels and other replaceables. Most of your important papers can be duplicated. Deeds, wills, list of credit cards passwords, passports and other information items are not going to be available to your heirs when you pass unless the box is held jointly. Your executor needs a court order and you won’t know since the will is off limits to you. For theft and fire safety, a home safe is more useful. You have the info and items at hand when you need them. A good safe costs $150-$250. It can be secured and hidden at home. It is fireproof and waterproof. Write the code down in a email to yourself. If you have fire or water damage, you can retrieve it from offsite computer or phone. You will need the $1.3 million later so use Buffett’s advice.


****************

Make America, “The Don” Great Again


Only a criminal looks to a pardon for a defense


Constitution: no clause for ‘absolute right’ to pardon


Trump thinks the govt is ‘conspiring against him.’


Trump gives Putin control of election: eliminates U.S. cyber advisor
Treason definition: ‘giving them aid and comfort within the United States’


“The election is going to be rigged—I’m going to be ‘honest’” 


Can Trump postpone Nov 2018 election using excuse of Putin meddling needs fixing?


************************

Only people who don’t know our government secrets are the people who pay for them.

Can single-payer health care work: US spends twice as much for fewer people than others


Trump advisor says his tariffs could wipe out tax cut benefits—higher costs for all.

SCAMS/SPINS:

Trump puts tolls on the Internet so we pay more and corp get special fast lane.


Jobs:
Coastal towns need sea walls by 2030: Antarctica’s ice melting at increasing rate. 

Who owns your account now?
Supremes decide you lose your vote in OH – state has power to purge you at will.
We don’t really own our Alexa Amazon account so we may not control recordings
Virtual currency gambling not going well—lost HALF value so far in 2018
Time-Warner to ATT—Cohen got it done: How Govt works against US
Fox to Comcast?

Can we trust Ari Melber to explain the legal case against POTUS? Steele?

Miracle:

The dictators met for a deal: Why pretend anymore—Trump TV has it right
"Regardless of what happens in that meeting between the two dictators" FoxNews calls it.


IAN
41 Watchung Plaza, B242
Montclair, NJ 07042
973.746.2014
Alerts